Sales jump 20% in Q3, but profit slips as costs and inventory climb
TCF POST Report
LOS ANGELES, Nov. 3, 2026. Revolve Group (NYSE: RVLV) posted its fastest customer growth in more than three years in the third quarter, but higher spending cut into profit and cash flow turned negative.
Net sales rose 20% to $356.0 million, up from $295.6 million a year earlier. Net income fell 27% to $15.5 million, and diluted earnings per share dropped to $0.20 from $0.29. Adjusted EBITDA slipped 7% to $23.5 million. Last year’s quarter included a $4.5 million insurance recovery, worth about $0.05 per share, which flatters the comparison.
The growth story
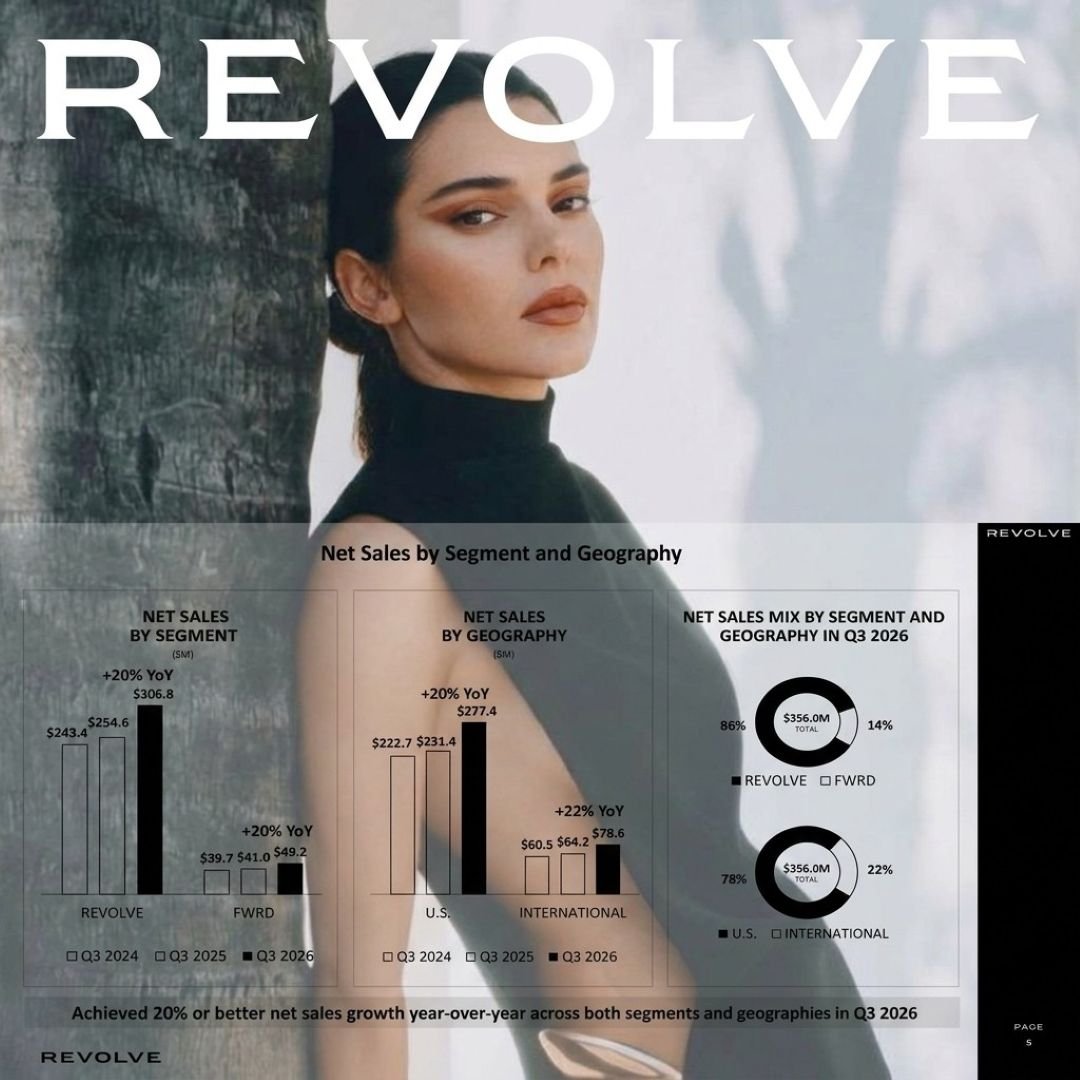
Co-CEO Mike Karanikolas said the company “delivered a strong third quarter” and pointed to sales growth of 20% or more across both segments and both domestic and international markets. He also highlighted an 18% rise in active customers, the fourth straight quarter of accelerating growth. Trailing-12-month active customers reached 3.24 million.
Co-CEO Michael Mente tied the momentum to brand building, physical retail expansion and partnerships. He cited the launch of REVOLVE Los Angeles and the inaugural REVOLVE Magazine. He also named a new joint venture with Donatella Versace and expanded deals with Kendall Jenner and Dwyane Wade. Mente said the company is pleased with its progress on longer-term investments meant to support future profitable growth.
By segment:
- REVOLVE: $306.8 million, up 20%
- FWRD: $49.2 million, up 20%
- Domestic: $277.4 million, up 20%
- International: $78.6 million, up 22%
Orders placed rose 19% to 2.75 million, helped by a lower return rate. Average order value fell 5% to $292, which the company blamed mainly on early sales of lower-priced Grow-Good beauty products.
The pressure points
- Margins: Gross margin slipped to 53.9% from 54.6%, though last year’s comparison included a large margin expansion.
- Costs: Selling and distribution costs rose to 17.8% of sales, driven by higher shipping rates. Marketing climbed to 14.3% from 13.7%, reflecting heavier performance and brand spending, including the push behind the REVOLVE Los Angeles label.
- Cash: Operating cash flow was negative $24.3 million, against positive $11.8 million a year ago. Free cash flow was negative $27.0 million. The company attributed the swing mainly to working capital.
- Inventory: Stock rose 23% to $293.3 million. Cash fell 10% to $284.6 million, and the balance sheet remains debt-free.
Outlook
October net sales grew by a mid-teen percentage. Management warned that November and December face tougher comparisons: last year’s fourth quarter grew 10% after a stronger holiday finish.
The company guided fourth-quarter gross margin down to 52.3%–52.8%, with marketing at 16.9% of sales. For the full year it narrowed gross margin to 53.9%–54.0%, raised its selling and distribution outlook to 17.5% of sales, and lifted general and administrative spending to $178 million. The outlook assumes no further IEEPA tariff refunds.
Management cited tariffs, inflation, geopolitical uncertainty and supply chain disruption as risks to consumer spending.