TCF POST Report
SAN FRANCISCO, Nov 5, 2026. a.k.a. Brands (NYSE: AKA), owner of Princess Polly, Culture Kings, Petal & Pup and mnml, reported third-quarter sales of $161.3 million, up 9.7% from $147.1 million a year earlier and 7.6% in constant currency. Adjusted EBITDA rose to $8.2 million from $7.0 million, a margin of 5.1% against 4.8%. But the net loss widened to $7.7 million, or $0.70 per share, from $5.0 million, or $0.46, a year ago.
Brand-wise performance
Princess Polly ended the quarter with 15 U.S. stores and plans to open at least six more in 2027, in addition to leading the U.K. growth. Management credited Culture Kings’ full-price, test-and-repeat model for the gross margin gain, and the brand will bring its retail experience to Puerto Rico this quarter. Petal & Pup has built its strongest distribution pipeline to date.
Growth built on volume
Sales growth came from more orders rather than bigger baskets. Orders rose 12.8% to 2.12 million, while average order value slipped 2.6% to $76. Active customers grew 8.8% to 4.43 million. Gross margin expanded about 100 basis points to 60.1%, helped by stronger full-price selling at the company’s streetwear brands and partly offset by higher inbound freight costs.
Why the loss widened
The larger loss traces largely to costs rather than weaker demand. Selling expenses rose to 32.4% of sales from 29.4%, including $5.3 million in one-time costs to move the company’s distribution center to Ohio. The operating loss reached $4.1 million, compared with $1.4 million a year earlier. Marketing spending edged up to 13.1% of sales from 12.6%, while general and administrative costs improved to 17.1% from 18.1%.
On the balance sheet, total debt fell 8.5% year over year to $101.9 million. Cash stood at $15.6 million, down from $20.3 million at the end of last year. Inventory was $95.4 million, slightly below the $96.7 million of a year ago but above the $86.2 million at year-end. Operating cash flow for the first nine months was $16.2 million, compared with $14.7 million a year earlier.
Market-wise performance
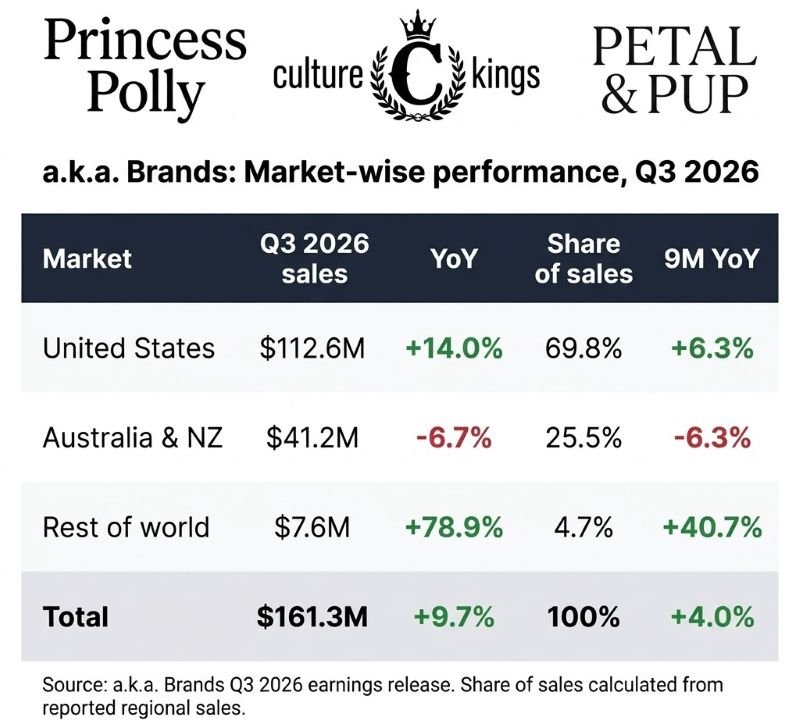
The United States carried the quarter. Sales there climbed 14.0% to $112.6 million, nearly 70% of the company’s revenue, and marked the U.S. business’s first double-digit gain since a.k.a. Brands overhauled its sourcing network last year. Nine-month U.S. sales are up a more modest 6.3%, which shows how much of the momentum arrived in the third quarter.
Australia and New Zealand moved the other way. Sales fell 6.7% to $41.2 million, and the nine-month decline of 6.3% shows a sustained trend rather than a one-quarter dip. The region still accounts for about a quarter of revenue, so its weakness is a real drag on the group.
The rest of the world was the fastest-growing segment, with sales up 78.9% to $7.6 million, led by Princess Polly’s growth in the U.K. Taken together, a.k.a. Brands is becoming more U.S.-centric, while Australia and New Zealand shrink and international expansion remains in its early stages.
Outlook
Management narrowed its full-year net sales guidance to $626 million to $632 million, from $625 million to $635 million, but cut adjusted EBITDA guidance to $29 million to $30 million, from $30 million to $32 million. Capital spending was trimmed to $16 million to $17 million. For the fourth quarter, the company expects sales of $172 million to $178 million and adjusted EBITDA of $7 million to $8 million.