TCF POST Analysis
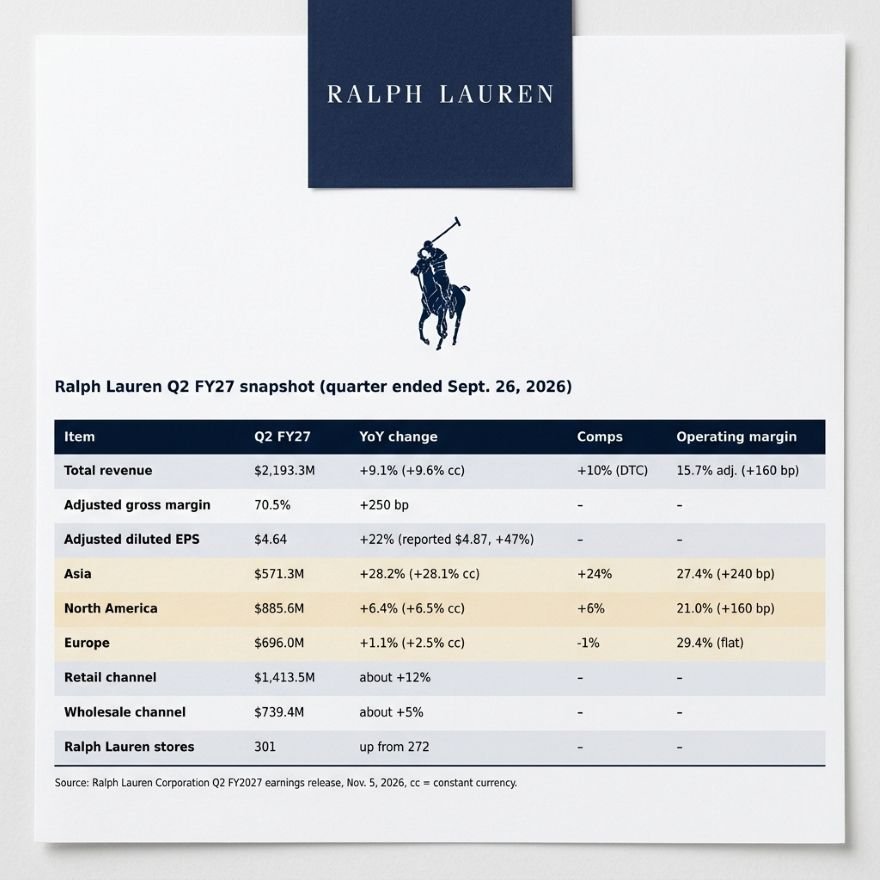
NEW YORK, Nov. 5, 2026: Ralph Lauren Corporation (NYSE: RL) reported second-quarter fiscal 2027 revenue up 9% to $2.19 billion (10% in constant currency) and raised its full-year guidance. Asia, where revenue rose 28%, led growth, and every region contributed. Higher prices, firmer full-price selling and an $82.3 million tariff refund lifted margins. Adjusted gross and operating margin expansion exceeded the company’s own outlook, even as spending on marketing and long-term growth initiatives continued.
"Through a dynamic global operating environment, we continue to invest in the strategic priorities that are bringing our Next Great Chapter: Drive plan to life — strengthening our brand desirability and delighting multi-generational customers in every geography around the world to drive sustainable long-term growth and value creation. Company's President and CEO Patrice Louvet said. "We remain confident in the strength of our brand, our teams and our diversified engines of growth through this fiscal year and beyond."
Market-wise performance
- Asia: Now makes about 26% of revenue, against 22% a year ago. China grew more than 35% on comps and new distribution. Brick-and-mortar comps rose 23% and digital comps 31%.
- North America: Wholesale rose 8%, including about 4 points from shipments pulled forward from the second half. Store comps rose 6% and digital 5%.
- Europe: Brick-and-mortar comps fell 4%, and a 9% digital gain was not enough to offset it. Wholesale rose 3% reported and 4% in constant currency.
- Licensing and other: Revenue fell about 9% to $40.4M.
Product-wise performance
- Core business: Up 10%.
- High-potential categories: Women’s apparel, outerwear and handbags grew low double digits in constant currency, ahead of the company average.
- Pricing: AUR rose 9% across the DTC network, driven by full-price selling and favorable geographic and channel mix.
- Launches: The Polo Blaze handbag line launched officially. Artist in Residence collaborations included Ralph Lauren x Gee’s Bend and a second Polo Ralph Lauren x TÓPA capsule. The U.S. Open Collection also launched.
- Not disclosed: The release gives no revenue split by category.
The brand-level activities
- Marketing: Sponsorships of Wimbledon, the U.S. Open and Goodwood Revival, a Spring 2027 women’s show in New York, and a Very Ralph documentary event in Seoul. Celebrity moments included BTS at MetLife Stadium.
- Reach: More than 72 million social followers, up mid-single digits. Brand awareness, consideration and net promoter score all improved. The company added 1.7 million new DTC consumers.
- Retail and hospitality: 22 new owned and partner stores opened, including Seaport in Boston (with the first Ralph’s Coffee in Massachusetts), Sloane Square in London, St. Tropez, and Hopson One in Beijing. The Ralph Lauren app launched in Japan.
- Store network: Concessions fell to 620 from 667, almost all in Asia, while directly operated Ralph Lauren stores in Asia rose to 186 from 167.
Sourcing and supply chain
- Tariff refunds: Gross profit includes $82.3M in refunds of tariffs paid under the International Emergency Economic Powers Act (IEEPA), which the U.S. Supreme Court ruled against. The company excluded this from adjusted figures and used $33.2M of the proceeds for charitable donations.
- Lower product costs: Cited as driver of the 250 bp adjusted gross margin gain, alongside AUR growth and geographic mix.
- Inventory: Inventory was $1.15 billion, down 9% from a year ago ($1.26 billion), though up from $1.01 billion in March. Inventory build in the first half used $134.2M of cash, against $281.6M a year earlier.
- Ongoing tariff risk: The company flags uncertainty over tariffs imposed under other U.S. trade authorities. It cites “mitigating sourcing strategies” as a risk factor.
- Supply chain risks: It lists the Uyghur Forced Labor Prevention Act, disrupted shipping routes, port strikes, Middle East conflict, factory closures and raw-material scarcity.
- Wholesale timing: Shipments were moved earlier from the second half. The company expects wholesale timing and off-price reductions to cost about 1 point of Q3 revenue growth.
Balance sheet and shareholder returns
- Cash: $1.8B in cash and short-term investments against $1.2B in debt.
- Operating cash flow: $618.2M for the half, versus $229.3M a year earlier.
- Capex: $114.2M for the half, versus $281.1M.
- Buybacks: $250M in Q2 and $500M year to date, completing the FY27 repurchase plan.
- Dividends: The quarterly dividend is $1.00 per share, up from $0.9125. Dividends plus buybacks returned more than $600M.
Outlook
Ralph Lauren now expects fiscal 2027 constant-currency revenue to grow about 6% to 7%, up from its earlier range of 5% to 6%. Fiscal 2027 is a 53-week year, and the extra week should add about 1 point to growth. Currency is expected to reduce revenue growth by 40 to 60 basis points. Operating margin is projected to expand 80 to 100 basis points in constant currency, driven mainly by gross margin. That expansion should be stronger in the first half because of the timing of marketing activations and wholesale shipments.
For the third quarter, the company expects constant-currency revenue growth of 3% to 4%. That includes about 1 point of drag from wholesale timing and strategic off-price reductions. Operating margin is expected to expand 50 to 70 basis points, with gross margin gains more than offsetting higher holiday marketing spend. The full-year tax rate is expected at 21% to 22%, and the third-quarter rate at 23% to 24%. Capital expenditure should run at about 4% to 5% of revenue.