TCF POST Analysis
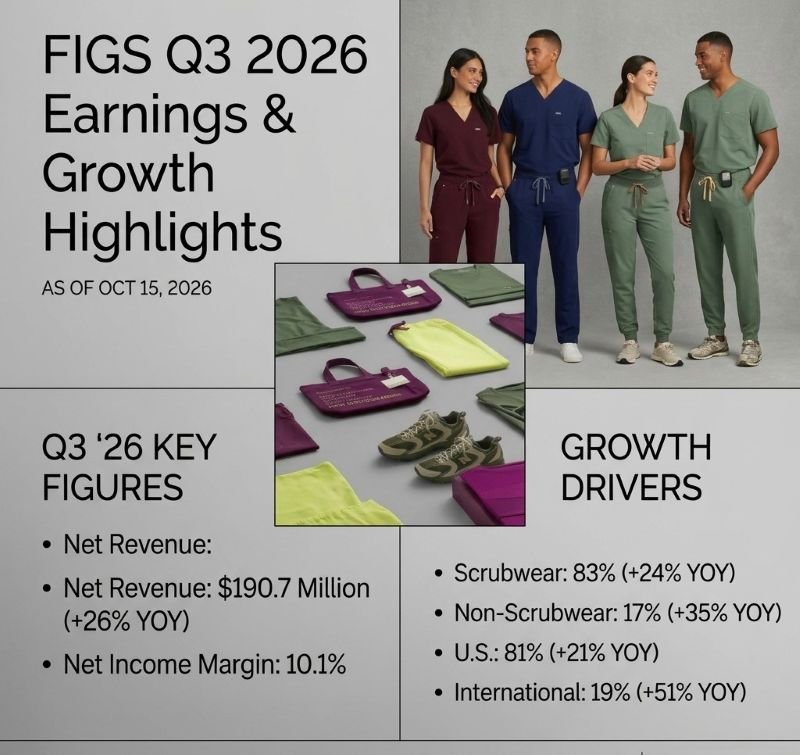
Santa Monica, 6 November 2026 - FIGS, the US direct-to-consumer healthcare apparel brand, raised its full-year 2026 outlook after a third quarter in which revenue grew 25.7% to $190.7 million. Net income more than doubled to $19.3 million. The mix of growth matters as much as the headline: international sales rose 51.4%, non-scrubwear products outgrew the core scrubs line, and customers spent more per order.
Products: scrubs still anchor the business, but diversification is paying off
Scrubwear sales rose 24.0% to $157.5 million, still about 83% of revenue. Non-scrubwear grew faster, up 34.6% to $33.2 million. Its share of sales rose to 17.4% from 16.2% a year earlier, and to 18.6% over the first nine months. Non-scrubwear supplied roughly a fifth of the quarter’s $39 million revenue increase.
Management attributes the higher average order value ($126, up 10.5%) to higher average unit retail from price rises and favourable product mix, plus lower discount and return rates. In other words, FIGS is selling at fuller prices with fewer discounts, which is a sign of brand strength rather than volume-chasing.
Brand health: more customers, each spending more
Active customers, defined as accounts with a purchase in the past 12 months, rose 14.3% to 3.18 million. Net revenue per active customer reached a record $236, up 12.9% from $209. Both customer count and spend per customer are growing at double-digit rates, which suggests the brand is winning new buyers while deepening loyalty among existing ones. CEO Trina Spear credited product, campaigns that resonate, a passionate community and strong industry fundamentals.
Marketing spend rose only 8.6% to $25.5 million, falling to 13.4% of revenue from 15.5%. Revenue is growing about three times faster than marketing outlay, and that gap explains much of the margin gain.
Markets: international is the growth engine
International sales contributed about $12.5 million, or roughly a third, of the quarter’s revenue growth, from a base under a fifth of the total. Over nine months, international revenue is up 56.4% to $103.0 million. The US is still growing at a healthy 20.8% but is clearly decelerating relative to overseas markets. The release doesn’t break out individual countries or regions, so which markets are driving the surge remains unanswered. It also lists B2B (through its TEAMS platform for healthcare institutions) and retail among its growth strategies, without giving figures.
Profitability: operating leverage, with some caveats
Operating expenses grew 13.9% against 25.7% revenue growth. Operating income rose to $22.2 million from $9.6 million, a margin of about 11.6% against 6.4%. Gross margin slipped 60 basis points, which management blames on tougher comparisons in returns processing and higher inventory reserves, partly offset by price increases and efficiency gains. Nine-month adjusted EBITDA excludes a $7.9 million refund of IEEPA tariffs paid on 2025 goods.
Outlook: growth expected to cool
FIGS now expects full-year revenue growth of about 23.5%, with Q4 up about 15%. It also expects an adjusted EBITDA margin of about 15.8%. Q4 growth would be a marked slowdown from the 25%-plus pace of the past four quarters. The release doesn’t explain the gap, and the guidance may be conservative given management’s stated “increased conviction” in Q4. The company flags risks including trade policy, dependence on a limited number of third-party suppliers, raw material costs and international expansion.