TCF POST Analysis
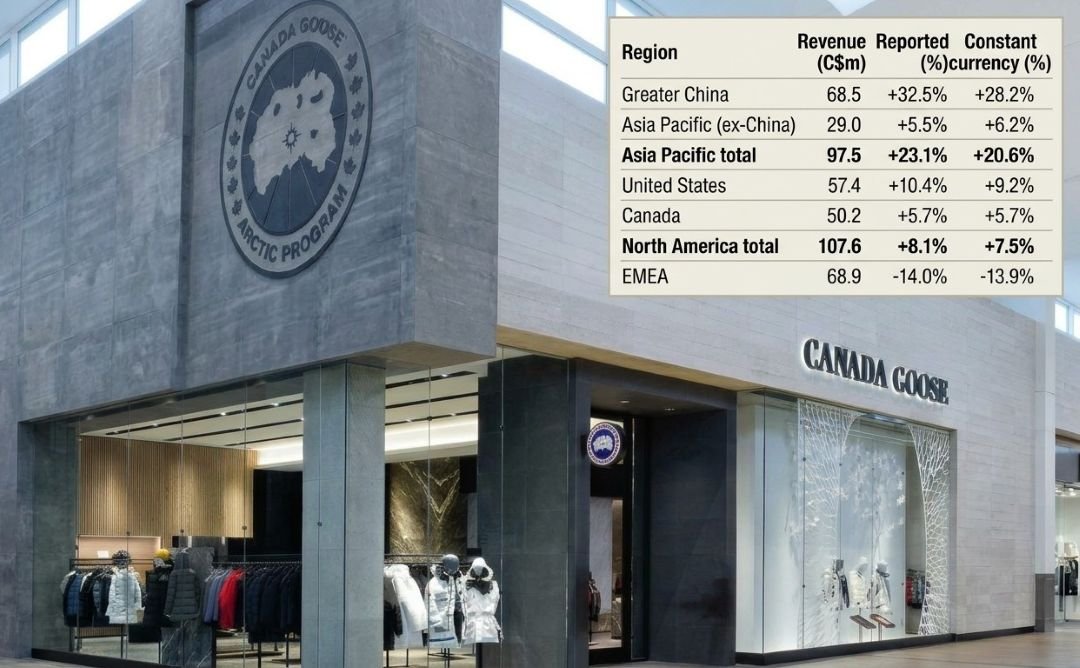
TORONTO, Nov. 5, 2026. Canada Goose grew sales 5.9% to C$274.0m in the quarter ended September 27, but a heavy marketing push and a bigger store footprint deepened its seasonal operating loss to C$21.6m. A 32.5% jump in Greater China offset a 14% drop in EMEA, and management reiterated its full-year targets.
Geography: Asia carries the quarter
Asia Pacific is now nearly as large as North America. It supplied C$18.3m of the C$15.2m total revenue increase, so the rest of the world shrank on net. Greater China was the standout, growing C$16.8m and now about a quarter of group revenue. EMEA was the only region in decline, which management tied to softer comparable store sales, weak traffic and low consumer confidence. The US grew 10.4%, ahead of Canada’s 5.7%, even as new US tariffs loom.
Channels: wholesale steady, DTC mixed
- Wholesale rose 4.6% to C$128.2m on higher order-book shipments, healthy in-season demand and Travel Retail growth.
- Direct-to-consumer (DTC) rose 2.7% to C$129.6m, but only 0.6% in constant currency. Comparable sales fell 7.5%: growth came from new stores and e-commerce (comps positive in North America and Asia Pacific), while comparable store sales were weak, particularly in EMEA.
- Other revenue jumped 62% to C$16.2m on friends-and-family activity.
- Two net new stores brought the permanent total to 94.
Products and brand: pushing beyond the parka
Apparel, rainwear and windwear delivered strong double-digit growth and are taking a larger share of the mix. New partnerships include ARCH Motorcycle Racing (co-founded by Keanu Reeves and Gard Hollinger; the brand’s first motorsport venture) and Ewan McGregor’s documentary series TRUE WIND, where Canada Goose is “Official Protective Gear Partner” and its Sea Mantra rainwear is featured. Baffin divested: the sale to L.P. Royer closed August 10, results now exclude the footwear business, and discontinued operations added a C$7.8m loss.
Profitability: higher margin, higher spend
- Gross margin rose to 66.8% from 64.0% on favourable product mix, production efficiencies and lower freight and duty costs. Gross profit grew 10.4% to C$182.9m.
- SG&A climbed to C$204.5m from C$183.3m on upper-funnel marketing and the expanded store network.
- Operating loss widened to C$21.6m from C$17.6m. Adjusted EBIT margin was -7.9% vs -5.5%.
Balance sheet and capital return
- Inventory was C$496.6m, up 8%, reflecting a wider assortment, lower-than-planned DTC sales, a larger wholesale book and pre-peak production. Turnover improved to 1.0x.
- Net debt rose to C$781.9m from C$707.1m, mainly on higher lease liabilities. Cash fell to C$87.1m from C$94.2m; cash used in operations was C$97.0m, typical ahead of the winter build.
- Buybacks: 2.09m shares repurchased for C$23.7m. A renewed buyback from November 10 allows up to 3.16m shares over twelve months.
Outlook: unchanged, with a tariff drag
Management reiterated fiscal 2027 guidance of low-single-digit revenue growth and an adjusted EBIT margin of 11% to 12%, implying a very large profit swing in peak winter, since the first-half margin was -31.7%. Guidance assumes gross margin expansion, falling SG&A as a share of revenue, and softer demand, traffic and travel than in fiscal 2026. US tariffs effective August 22, 2026 will cost about 100 basis points of adjusted EBIT margin.
Bottom line
Asia, and China in particular, is driving growth while Europe weakens and store comparables fall. Canada Goose is betting that non-parka categories, celebrity-linked partnerships and a heavy holiday marketing push can deliver a back-half recovery big enough to hit its 11-12% margin target.